Buying a Home Near Benbrook Lake: Flood Zones and Insurance
Do you need flood insurance to buy a home near Benbrook Lake?
If the home sits in a FEMA Special Flood Hazard Area and you’re using a federally backed mortgage, yes — flood insurance is required. Not every home near Benbrook Lake is in that zone, so the first step is checking the property’s exact flood designation on FEMA’s Flood Map Service Center. The good news for buyers here: the City of Benbrook earns a Community Rating System class 6, which gives floodplain properties a 20% discount on their NFIP flood insurance premiums. Verify the zone and get a real insurance quote before your option period ends.
By The Chad Smith Team | September 22, 2026
Buying near Benbrook Lake means buying near water, and water changes the math. Benbrook Lake is a U.S. Army Corps of Engineers reservoir on the southwest edge of Fort Worth, and homes around it can carry flood considerations that a landlocked property never does. That’s not a reason to walk away — plenty of people happily own near the lake — but it is a reason to do your homework before you write an offer.
Here’s what buyers need to understand about flood zones and insurance around Benbrook Lake.
Flood zone comes first — and it’s property-specific
The single most important thing to know: flood risk near Benbrook Lake is determined lot by lot, not by the neighborhood. Two homes on the same street can carry different flood designations depending on their elevation and distance from the water.
FEMA maps every property into a flood zone. The ones that matter most are the Special Flood Hazard Areas — zones labeled A (including AE) and V — which represent high-risk areas. If a home is in one of these zones and you’re financing with a federally backed mortgage, your lender will require you to carry flood insurance through the National Flood Insurance Program (NFIP).
Before you get attached to a specific home, look up its flood zone at FEMA’s Flood Map Service Center (msc.fema.gov). Enter the address and you’ll see its designation. This is a five-minute check that shapes your entire budget, so do it early — ideally before you even write the offer, and definitely within your option period.
Benbrook gives buyers a real insurance advantage
Here’s a piece of good news specific to this area. The City of Benbrook participates in the NFIP’s Community Rating System (CRS) — a voluntary program that rewards communities for floodplain management that exceeds the federal minimum. Benbrook has earned a CRS class 6, which translates to a 20% discount on NFIP flood insurance premiums for properties in the floodplain.
That discount is meaningful. On a policy that might otherwise cost several hundred to a couple thousand dollars a year, 20% off adds up over the life of ownership. It’s one of the reasons buying inside Benbrook’s city limits near the lake can pencil out better than a floodplain property in a community without a strong CRS rating.
What flood insurance actually costs in Texas
Flood insurance is priced separately from your regular homeowners policy — and this trips up a lot of first-time lake buyers. Your standard homeowners insurance does not cover rising floodwater. You need a dedicated flood policy for that. (For everything your homeowners policy does cover, and what drives premiums in North Texas, see our guide to homeowners insurance in North Texas.)
Some current Texas benchmarks to set expectations:
• The average NFIP flood policy in Texas runs around $779 a year, close to the national average.
• Homeowners in high-risk flood zones pay about 52% more than those in moderate- and low-risk areas.
• In a Zone AE, policies can range widely — from a few hundred dollars to well over $1,500 a year — depending on the specific property.
A big shift is now in full effect: FEMA’s Risk Rating 2.0 is fully implemented as of 2026. Instead of pricing mainly off the flood-zone label, it now uses individualized factors — a property’s specific flood exposure, its elevation, its replacement cost, and its distance from water. About 80% of Texas policyholders saw an average premium increase of up to $120 a year under the new system, though some elevated or lower-risk homes actually pay less.
The practical takeaway: you can’t estimate flood insurance from the zone alone anymore. Two homes in the same Zone AE can be priced very differently based on elevation. That’s why a real quote on the specific property matters far more than a rule of thumb.
Elevation is the pricing lever
Under Risk Rating 2.0, how high the home sits relative to expected flood levels is one of the biggest cost factors. A home built higher — or elevated, or built to modern standards — often costs meaningfully less to insure than a similar home sitting lower nearby.
For older homes near the lake, an Elevation Certificate can still help. It’s a document prepared by a licensed surveyor that establishes the home’s elevation, and while it’s no longer mandatory for NFIP rating the way it once was, it can sometimes support a better rate or a Letter of Map Amendment if a home was mapped into a zone it doesn’t actually belong in. If you’re buying an older lakeside home, ask whether one exists — and know that a current property survey is worth having regardless. Our guide to property surveys in Texas explains what a survey should show, including how the structure sits on the lot.
Your due-diligence checklist for a Benbrook Lake home
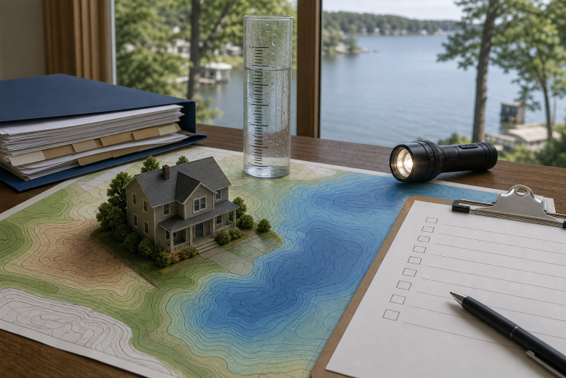
Before you commit, run through these during your option period — the window our guide to the Texas option period explains in full:
1. Pull the FEMA flood zone for the exact address at msc.fema.gov.
2. Get a real flood insurance quote on that specific property, not a zone-based estimate.
3. Confirm the CRS discount applies — it does for floodplain properties inside Benbrook city limits.
4. Ask about an Elevation Certificate or survey, especially on older homes.
5. Check prior flood history and any past claims on the property.
6. Budget both policies — homeowners and flood — into your monthly cost.
The bottom line for lake buyers
A home near Benbrook Lake can be a wonderful place to own — you just need to price the flood picture accurately before you buy, not after. The zone, the elevation, the CRS discount, and a real quote on the specific property tell you what your true cost of ownership will be.
Every lakeside property is different, and the only way to know your real number is to check the zone and pull a quote on that exact home. That’s exactly what we help buyers do around Benbrook Lake before they write an offer — confirm the flood designation, factor in the CRS discount, and make sure the full cost, both policies included, fits the budget. If you’re weighing a home near the lake, we’re happy to walk you through it. Reach out anytime.
Frequently Asked Questions
Is flood insurance required for a home near Benbrook Lake?
It’s required if the home is in a FEMA Special Flood Hazard Area (zones A, AE, or V) and you’re using a federally backed mortgage. Homes outside those zones aren’t required to carry it, though it can still be a smart purchase near water. Always check the property’s specific flood zone first.
How much is flood insurance around Benbrook?
The average NFIP policy in Texas runs around $779 a year, but high-risk zones pay roughly 52% more, and Zone AE policies vary widely by elevation. Benbrook’s Community Rating System class 6 gives floodplain properties a 20% discount, so get a real quote on the specific home.
What is Benbrook’s CRS discount?
The City of Benbrook participates in the NFIP Community Rating System and holds a class 6 rating, which earns a 20% discount on NFIP flood insurance premiums for properties in the floodplain. It reflects the city’s floodplain management exceeding federal minimums.
Does my homeowners insurance cover flooding?
No. Standard homeowners insurance does not cover rising floodwater. You need a separate flood policy, typically through the NFIP, to be covered for flood damage near the lake.
How do I find out a home’s flood zone?
Look up the address on FEMA’s Flood Map Service Center at msc.fema.gov. It shows the property’s flood zone designation, which determines whether flood insurance is required and heavily influences the cost.
About The Chad Smith Team
The Chad Smith Team at Realty of America is one of the top-producing real estate teams in the Dallas-Fort Worth Metroplex, with more than 22 years of experience, 2,915 homes sold, and recognition by RealTrends among the top 1% of real estate professionals nationwide. The team helps first-time buyers, sellers, relocation clients, and new construction buyers throughout Arlington, Mansfield, Fort Worth, Midlothian, Waxahachie, and surrounding DFW communities. Through this blog, the Chad Smith Team shares expert market insights and practical advice to help North Texas buyers and sellers make informed real estate decisions.